
Turn Generational Insights into Stronger Banking Relationships
By Jessica Kendall, Contributor at The Financial Brand
Simple Subscribe
Subscribe Now!
Generational differences can tell banks and credit unions what customers need, but the bigger challenge may be acting on that knowledge at the right moments.
Gen Z, Millennials, Gen X, and Baby Boomers bring different financial priorities and expectations to the relationship, from building financial confidence to managing complex household finances to protecting accumulated wealth. Yet across generations, consumers increasingly judge that relationship through digital channels, according to Alkami’s 2026 Generational Trends in Digital Banking study.
Key insight: Account opening, everyday banking, personalized recommendations, financial guidance, and fraud protection all influence whether a customer sees a financial institution as relevant and trustworthy.
Customer data and behavioral signals can make digital experiences more timely and useful, while preserving the human support customers want when decisions become more complicated. The institutions that connect relevance to action can create more opportunities to deepen existing relationships.
Key Takeaways
- Design for life stage, not age alone. Generational patterns provide useful context, but financial priorities vary within each generation. Experiences should respond to individual behaviors, needs, and goals.
- Treat onboarding as the beginning of relationship expansion. Sixty-eight percent of digital banking Americans prefer mobile account opening, while 41% say they would be most likely to open another account with their primary provider if account opening took five minutes or less.
- Make personalization useful enough to act on. Forty-four percent want their primary provider to do a better job anticipating their financial needs and goals, creating a clear case for better timing, context, and relevance.
- Put protection alongside personalization. Ninety-five percent say protecting their data from fraudsters or hackers is important, while 67% are comfortable with AI identifying suspicious transactions and notifying them.
- Bring relationship strengths into digital channels. Trust, local knowledge, and knowledgeable support remain valuable differentiators for regional and community financial institutions. The digital experience needs to reinforce those advantages rather than operate separately from them.
Make the First Digital Moment Count
The relationship often begins before a customer ever talks with a banker.
Forty-three percent of digital banking Americans say they currently use their financial provider because it was recommended by a friend or family member. But a referral is just a starting point. Account opening determines what happens next.
The research shows that customers expect account opening to be convenient and easy to complete on their preferred device. Sixty-eight percent of digital banking Americans prefer using a mobile device to open a checking or savings account online.
Key insight: Convenience is about more than the device. Sixty-four percent of consumers who opened a deposit account in the past year took more than 5 minutes to apply and access it, with the average process taking 7.4 minutes. And while speed is clearly a priority, fewer than 11% of banks and credit unions currently offer a 5-minute digital setup.
That creates a particularly interesting growth opportunity. Forty-one percent say they would be most likely to open an additional account with their primary financial institution if the process took five minutes or less. Account opening, in other words, is not just an acquisition process. It can also be a mechanism for relationship expansion.
The experience also needs to work across channels. Customers should be able to start on a mobile device, continue on another channel, see where an application stands, and get help without having to start over.
Key takeaway: This means measuring onboarding beyond application completion. It’s about what the experience makes possible next. A customer who opens an account should have an obvious path into funding, saving, payments, credit, or another relevant part of the relationship.
Turn Relevance into Relationship Growth
Once the account is open, the institution has to demonstrate that it understands the customer behind it.
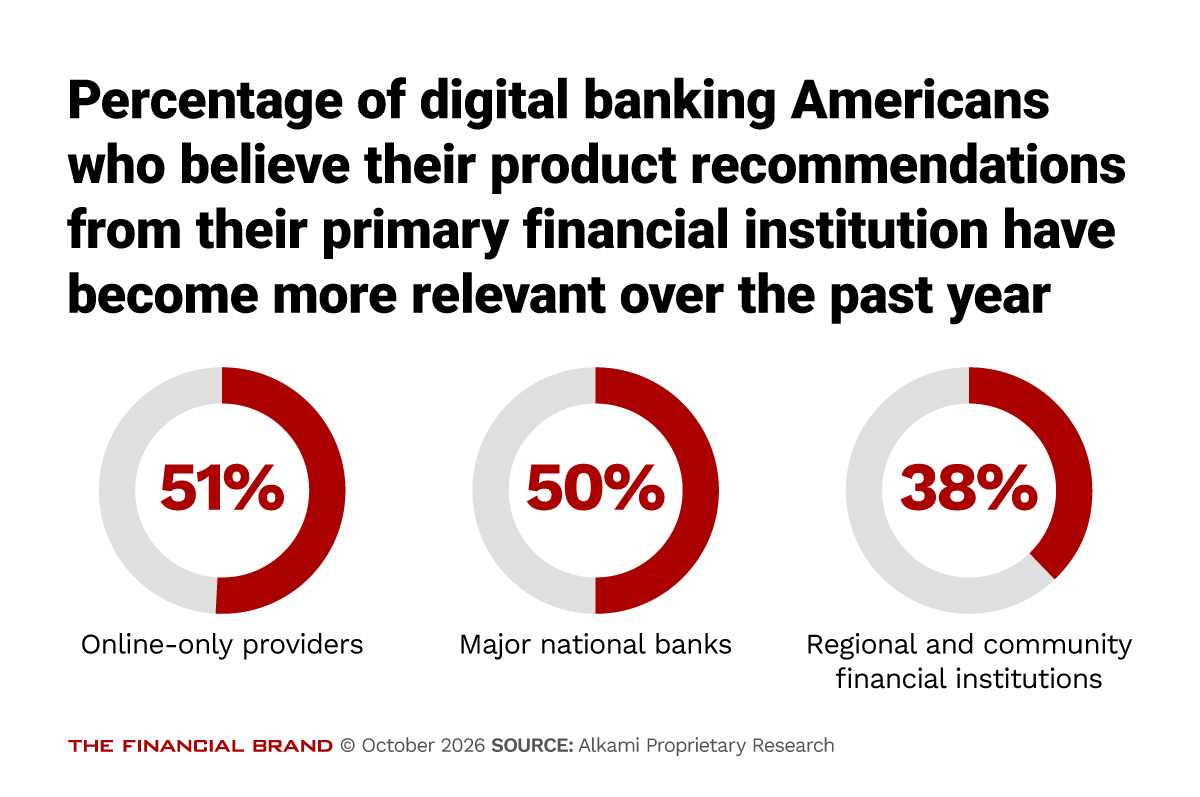
Forty-seven percent of digital banking Americans say product recommendations from their primary provider have become more relevant over the past year. But that experience varies by institution type. The figure reaches 51% for online-only providers and 50% for major national banks, compared with 38% for regional and community financial institutions.
For retail banking leaders, that gap points to a practical challenge: having customer data is not the same as turning it into useful engagement.
Customers are asking for help that feels connected to their actual financial lives. Fifty-two percent look to their trusted financial partner for guidance, while 51% say managing finances takes an emotional toll. Their feedback to banks focuses on making investing, saving, financial planning, and everyday money decisions easier to understand.
The strongest opportunities may be about improving the timing and context around them. Customers are most likely to act on personalized offers through the mobile banking app, followed by online banking, email, text messages, and social media.
Generational differences can help shape those interactions. Gen Z shows interest in credit-building and investment products. Millennials show demand across credit, investing, deposits, auto loans, and mortgages. Gen X’s interests include credit, investment, auto lending, cards, and CDs, while Baby Boomers show interest in investments, auto loans, CDs, and P2P payments.
Key insight: The research also makes clear that generic generational messaging will not be enough. Forty-four percent of consumers wish their primary provider did a better job anticipating their financial needs and goals.
The useful application of segmentation is to identify a relevant possibility, then use individual data and behavior to determine whether that possibility actually fits.
Use Digital and AI to Deepen Trust
Digital banking has become the primary relationship layer even as branches remain important.
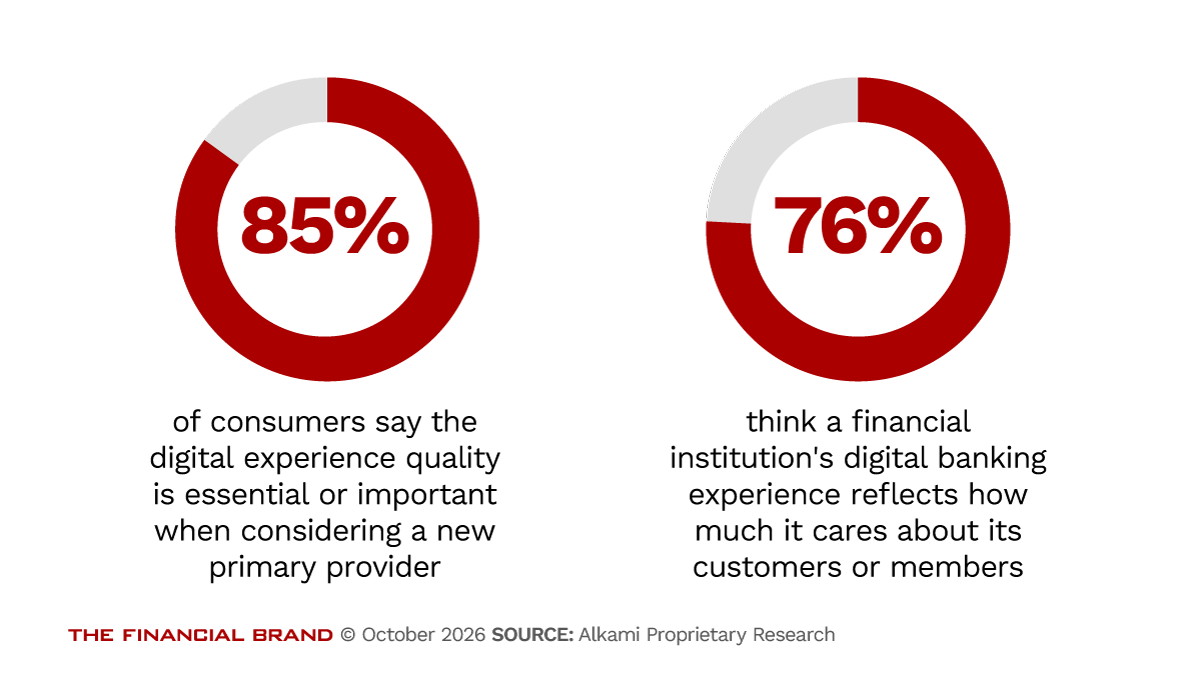
Seventy-six percent of respondents say the digital banking experience reflects how much a financial institution cares about its customers or members. Eighty-five percent say digital experience quality is essential or important when considering a new primary provider.
In fact, roughly half say they would change providers for a much better digital experience, and 31% have already opened an account elsewhere after a poor digital experience.
That puts digital experience in a different category from a technology project. It is part of how customers assess the institution itself.
The same principle applies to AI. Fifty-one percent of consumers are comfortable with their financial data being processed by AI if it produces a better experience. That rises to 57% among Gen Z but falls to 38% among Baby Boomers.
More importantly, 67% say they would feel comfortable with a protective AI strategy that identifies suspicious or fraudulent transactions and notifies them.
Key insight: To drive AI adoption, financial institutions should start with the customer problem. AI can help save time, prevent mistakes, support financial decisions, or protect money. Those use cases give customers a reason to accept the technology rather than asking them to trust AI simply because the institution has deployed it.
That matters as financial relationships become more fragmented.
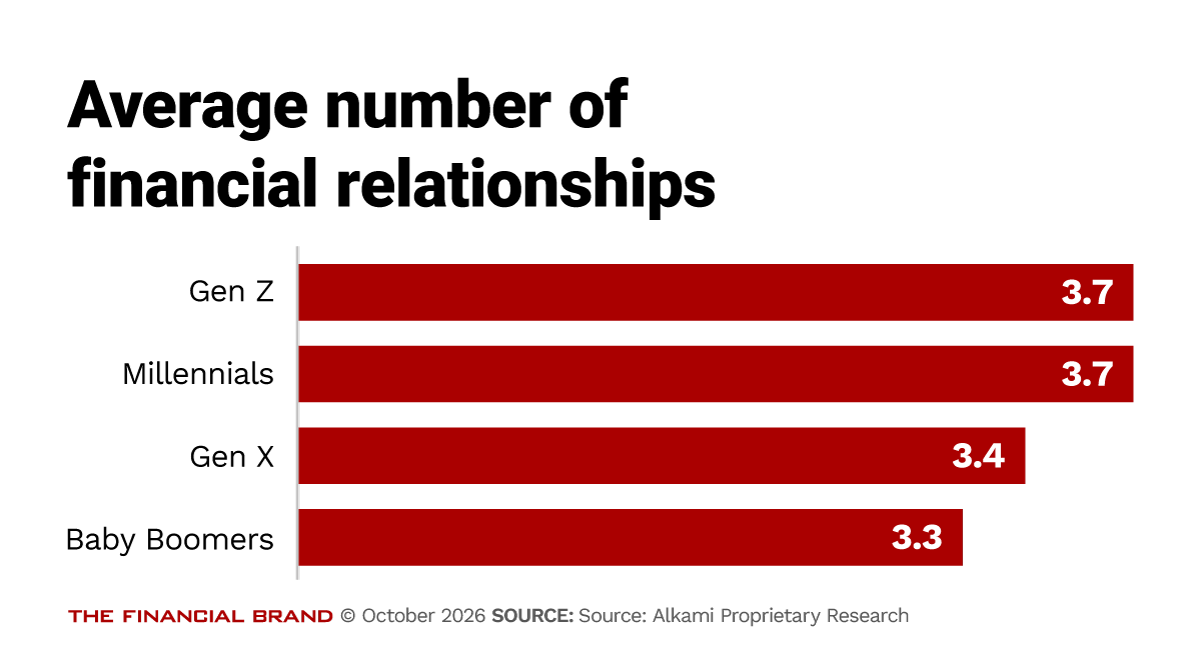
The study finds that customers maintain multiple financial relationships, averaging between 3.3 and 3.7 providers depending on generation. At the same time, the average length of banking relationships has declined for Millennials, Gen X, and Baby Boomers compared with the previous year.
Regional and community financial institutions have meaningful relationship assets to bring into this environment: trust, local knowledge, community connection, and long-standing customer relationships. The challenge is making those qualities visible in digital interactions, from the first account opening through personalized guidance and fraud protection.
Bottom line: The generational research provides a useful map of what different customers may need. The real work for banking leaders is turning that context into better moments: a simpler first interaction, a more relevant next step, useful guidance when finances become complicated, and protection when the stakes are high.
That is how digital banking becomes more than a transaction channel. It becomes the place where the institution proves it understands the customer and gives them reasons to keep bringing more of their financial life into the relationship.


