
How U.S. Bank Drives Untapped Growth in Markets It Already Knows Well
By Steve Cocheo, Senior Executive Editor at The Financial Brand
Simple Subscribe
Subscribe Now!
U.S. Bank has spent the last several years optimizing its branch network. Now, in the words of branch network head Sekou Kaalund, “We’re pivoting to offense again.”
Slimming down days are done. Today, the nation’s number five bank by asset size has 2,108 branches in 26 states, down almost a third from 3,223 in 2015. The trend reflects closures, combinations and relocations, according to Kaalund, head of branch and small business banking.
One factor: Many of the closures have been of in-store branches, a strategy eclipsed by technology.
Before we had our digital tools, in-store branches provided access to people over the weekends and after hours, “and you don’t need that anymore,” Gunjan Kedia, president, CEO and director, told analysts during a January earnings briefing.
Time to grow: Now, the bank is opening new branches again.
“It’s not to say that we wouldn’t ever close a branch again,” says Kaalund, “but our focus now is more on investing in branches in our markets. And we have the opportunity within our footprint to create better density.”
Key insight: Kaalund uses the word “densifying” to describe U.S. Bank’s present branching strategy. Meanwhile other large banks have been dropping in offices to establish and then build out beachheads in new markets.
But Kaalund says U.S. Bank prefers to put more chips, if you will, on the spots it knows are producing, rather than spreading them around thinly.
Key risk: Once someone establishes a relationship with another provider, their one-time primary financial institution risks slipping into second place — or even losing the relationship entirely.
Need to Know:
- As the pace of consolidation has slowed, U.S. Bank is investing in branches, everything from updates to appearance, branch technology and the flow of customer interactions to complete tear-it-down-to-the-studs rebuilds.
- In 2024, the bank invested over $85 million across about 90 branches, in 2025 over $335 million across approximately 300 branches. Over the next ten years, U.S. Bank plans to spend $200 million annually on refreshment and modernization.
- The emphasis on revamps and new builds is providing more space for conversations, less space for transactional needs, and in general turning branches into hubs that can produce retail, wealth management, and small business connections.
- Accompanying the change of purpose is a focus on what Kaalund calls “branch choreography” — moving the customer from the front of the branch to the person or persons who can address their needs, be it a business specialist or a retirement savings advisor.
U.S. Bank Digital Chops and Branch Focus Equals ‘Phygital’ Strategy
Kaalund says the bank realizes that, while digital technology has taken over much of rote banking, people of all ages still want to be able to visit a banker for advice, to solve problems, to handle major moves like buying a house.
“The best results come when you have human plus digital,” says Kaalund. “Money’s personal. Even though your money’s not in a particular branch, symbolically it is.”
This is especially significant in that U.S. Bank is a leading digital player. For example, the bank’s noted virtual assistant, U.S. Bank Smart Assistant, and its mobile app rank are highly respected. The bank’s innovation and digital leaders are industry bellwethers.
The two sides of U.S. Bank come together in various ways. One is the bank’s “co-browse” feature.
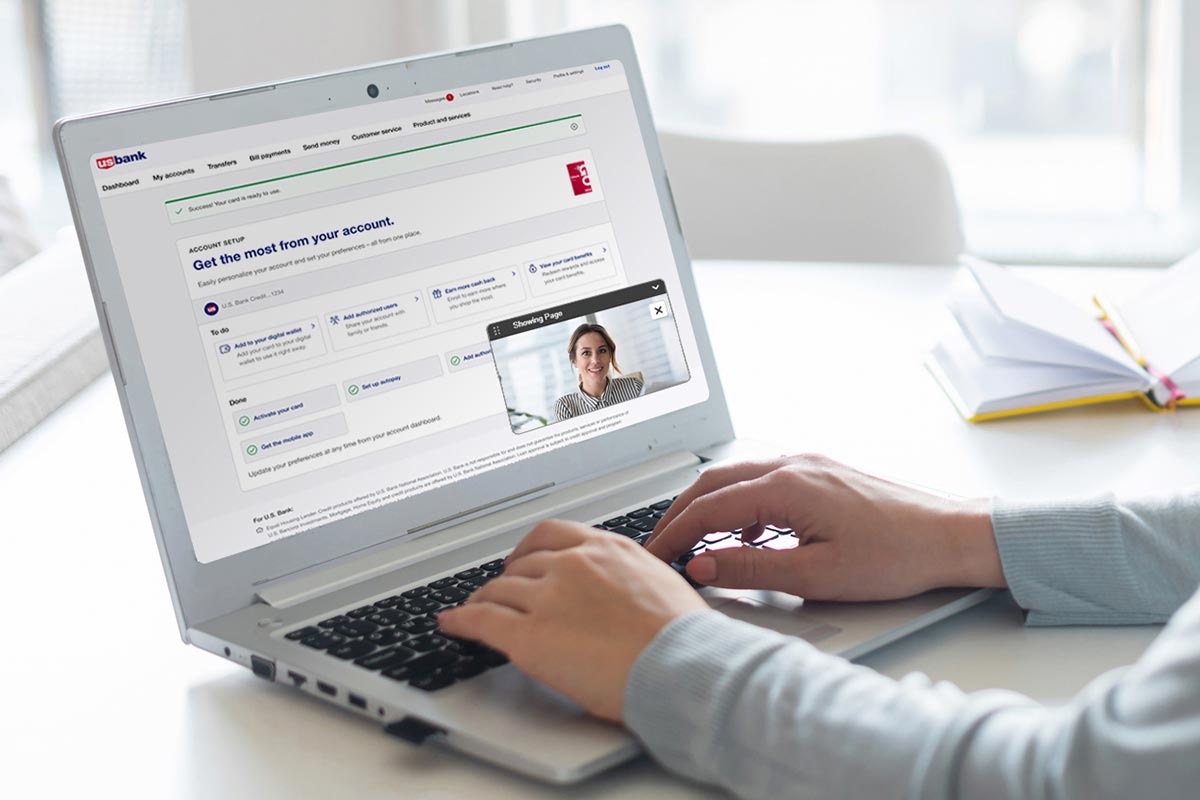
This functionality enables a customer using the bank’s mobile app or desktop app to ask for live help from a branch officer or other U.S. Bank banker. The banker can see, but not control, the customer’s screen, and appears in a window-in-a-window — a remote approximation of an in-person tutoring session.
“From the comfort of your couch, you can still have that personal touch,” says Kaalund.
Read more: ‘The Branch Is Dead’ … Is Dead: Have We Reached National Branch Equilibrium?
Densifying the U.S. Bank Footprint
Some dramatic branch expansion plans have emerged regularly from JPMorgan Chase and other major players.
U.S. Bank hasn’t made such sweeping pronouncements. Instead, it has been selectively adding locations where it makes sense to do so.
U.S. Bank’s target: During the earnings briefing Kedia underscored that the bank’s overall branching strategy is “to try and get to top five market share in the places we are already in.”
Kaalund explains that picking new markets and launching an anemic entry of one or two branches as a foothold doesn’t produce the scale the bank wants.
Some examples:
Case study 1: California. The bank opened four new branches in greater Los Angeles in 2025. This came on top of the company’s purchase of Union Bank in 2022, which made its California network the state’s fourth-largest — 582 locations currently. More new branches are coming in California in 2026.
Case study 2: Arizona. The bank opened three branches in Phoenix in 2025 and another in early 2026, bringing the total to 50 in the city. It plans to open additional branches in 2026.
Case study 3: Charlotte, N.C. Last year the bank opened its seventh branch in the city (headquarters of Bank of America) and it wants to double that presence.
Branch siting decisions aim to put branches within a 20-minute drive of the customers an office is expected to serve, according to Kaalund. This criteria varies in terms of actual mileage because traffic conditions in urban areas versus suburban areas, he points out. He adds that different branches may be sited on different rationales — some will lend themselves better to consumer traffic, others to small business clients, and some to a balanced mix.
Read more:
Connective Intelligence, the Ace that U.S. Bank Keeps Up Its Sleeve
Key question: How do banks “skate to where the puck is going,” perhaps a few years off?
U.S. Bank’s answer: Kaalund says the clues can be as close as the bank’s own commercial loan and commercial real estate functions.
“We want to anticipate where development is happening and where people will be going,” Kaalund explains. Lenders have their eyes and ears open all the time
Kaalund is originally from Charlotte, and he cites that market as a touchstone.
It’s a city that’s expanding outward, and he says the bank is involved in development finance in both commercial and housing. Lenders know where building permits are being sought, where they are being granted, when projects are starting.
This is valuable intelligence that Kaalund says U.S. Bank tries to tap as the picture becomes clearer.
Sometimes that means a new branch will be sited ahead of the development coming to full fruition. Kaalund says the bank isn’t troubled by that.
“It may take you 12-18 months to build a branch there, but by the time the development has commenced and turned the area into a hot spot, you are already in, seen as the bank that’s there to serve small businesses and consumers.”
Read next: Wells Fargo Is Leaning Hard Into Branches Again – And With a Fresh Take


