
How TD Bank is Attacking Its Primacy Challenge in the U.S.
By Steve Cocheo, Senior Executive Editor at The Financial Brand
Simple Subscribe
Subscribe Now!
TD Bank U.S. has been calling its branches “stores” for a couple of decades, since its acquisition in 2008 by Canada’s TD Bank Financial Group. That usage goes back to the bank’s origin as Commerce Bank, whose founder, Vernon Hill, came from the fast-food business. He liked “stores” better in part because it better fit his concept of establishing the company as “America’s Most Convenient Bank,” a motto TD used until its recent rebrand to “More Human.”
Once the label was leading edge, unbankerly by design. But is “store” still a good term?
“That’s actually something we’re talking actively about,” says Jennie Platt, CMO at TD Bank U.S.
At the time, “it was meant to signal a different experience that clients were going to have when they walked into our locations,” says Platt, whose financial marketing career includes long stints at Citibank and American Express.
“But particularly in the U.S. banking market, there’s a trend now toward branches as financial centers, and more advice-based content and experiences,” says Platt. She says TD “has got to focus on relationship-deepening.”
TD’s new focus. At TD, the stress is on building primacy in the face of fragmented financial experiences, and that means change.
“We do a great job bringing customers in the door on a single-product basis,” says Platt. “But we’re trying to get better at leveraging data and all of our connected strategies across our business lines to come up with the value proposition, and then, of course, the targeting and marketing strategies to support it.”
Platt says that products, data and marketing all must come together.
“We need to embrace digital to get the simple transactions to be really frictionless, to get mobile adoption even higher, so we can free up the capacity of our frontline bankers to focus on delivering advice and focusing on relationship depth,” says Platt. “In this way we can be a trust-based, end-to-end financial services player.”
Need to Know:
- TD Bank U.S. is among the country’s top ten banks by assets.
- Deeper relationships with customers was one of three performance pillars TD committed to during its fall 2025 investor day.
- Platt heads “a centralized end-to-end marketing function with full funnel responsibilities for brand, sponsorships, distribution marketing, product marketing, across all of our lines of business.”
Seeking Primacy at Multiple Levels
In spite of Americans’ mix-and-match proclivities, Platt believes primacy is a realistic goal, and better for both the bank and customers.
Key point: “We can do the best job possible when we are able to service more of their wallet, because it all works better together,” says Platt. “When we have more data on you, we can be more personalized.”
Platt says there are multiple paths to building deeper, broader relationships. “I’m a big believer that there’s no one silver bullet for being able to cross-sell effectively,” she says. She gives two examples.
First up: Cross-selling credit cards into the bank’s deposit base, an effort that’s been accelerated over the last year. TD wants to scale up its credit card business.
Platt says a key part of the effort was for her marketing operation and the product side to come together. Questions had to be asked and answered: Do we have the right product set? What are the right offers? How do we make them competitive and compelling?
This in turn has driven issues like improving the digital application flow. But in-store experiences must also be considered, according to Platt: Are offers being promoted sufficiently? Is the front-line force trained enough to promote the value of their cards?
All this ties into underwriting, too. “These prospects are our own deposit customers. We have more data on them than we would have on a pure prospect where we would just be relying on a FICO score,” says Platt.
Second: Cross-selling wealth management services from the deposit base. TD is emphasizing both wealth services and service for mass affluent customers.
A pilot program that’s underway is TD Premier.
“We actually created a new value proposition. When someone enrolls in the program, they get a dedicated relationship banker,” says Platt. “This is for deposit clients who are on the threshold of opportunity, that we can see over time becoming wealth management clients. Ideally, we will cross-sell them into wealth management if it’s the right thing for them at the right time.”
Platt says early returns on TD Premier indicate the concept is doing well and illustrates how centralizing accounts at TD works to the consumer’s advantage.
Read more: The Hidden Cost of Siloed Data in Financial Services
Two Approaches to Digital Marketing
JPMorgan Chase has recently been running video spots promoting their branches as “Places for People.” In one ad, the main character constantly collides with digital services, including a robot barista and a driverless taxi. He’s exasperated, and he eventually gets to talk to a live human being at his Chase branch.
Differing vantage points on tech. “Chase’s ad positioning is a little bit like ‘Technology’s frustrating, so come to a branch’,” says Platt. “Our view is more nuanced than that.”
In fact, a current video spot launched by TD promotes the idea of human-technology synergy. A small, boxy robot, reminiscent of the Disney character WALL-E, sets out on a cross-town journey, attracting humans’ curiosity: What’s inside? Where is the bot going? At one point, it gets caught up in a rut, and is assisted out by a human who kneels to help it. Continuing on, it reaches its destination: a crossing guard, who flips the top of the machine and pulls out the beverage it was delivering — after paying for it with his TD Bank card via digital wallet.
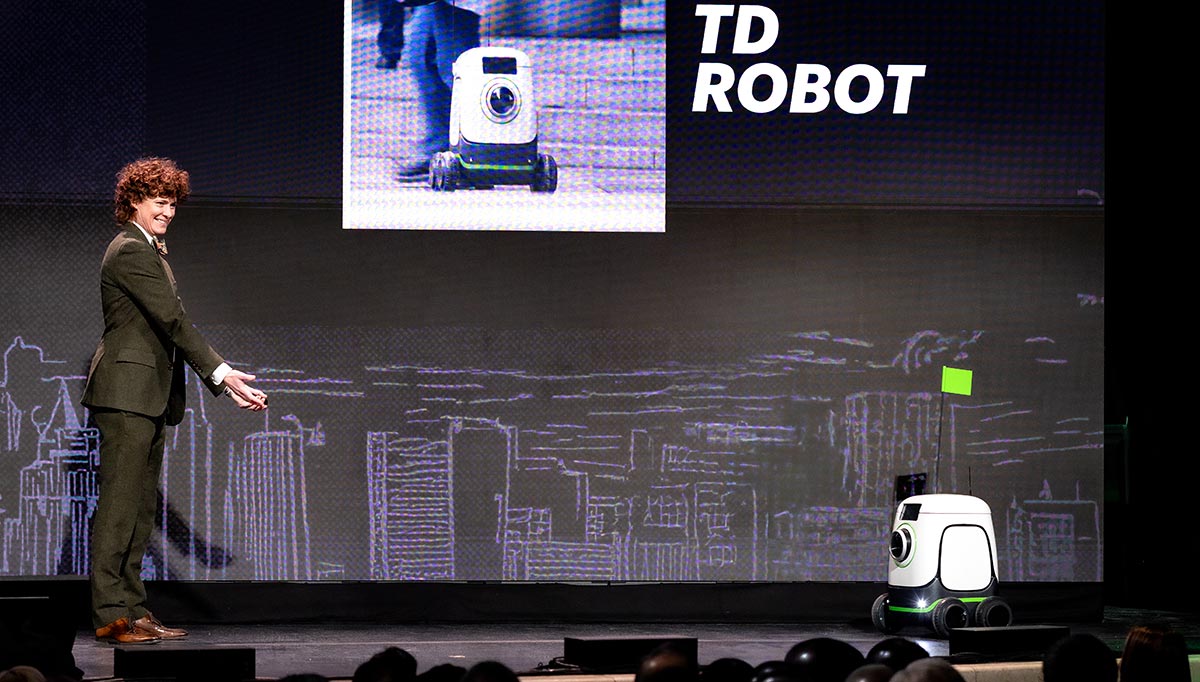 TD Bank U.S. CMO Jennie Platt greets the robot that starred in the bank’s inaugural “More Human” video. During the shoot the director called it “Little Fella,” but the robot doesn’t have an official name. “We’re not trying to make the robot a mascot nor is it going to star in every future ad,” says Platt. “It was meant to be an analogy for technology in the world we’re living in, but people love him.” There are actually three of the mocked-up bots, two in Toronto and one sharing Platt’s office in Manhattan.
The tagline for the ad, and the bank’s current theme, is “More Human,” which builds on past campaigns.
“What we’re saying is, ‘We’re all in on technology, but we’re going to design it in a way that’s very human. It’s ‘digital first, human-always’,” says Platt.
In this approach, personalization on all fronts is the goal. “We are investing a lot in the ability to understand who the client is when they come into our mobile app and making sure that the thing that we’re talking to them about in marketing placements recognizes who they are,” says Platt. For example, if a life stage change is detected, or a windfall has hit their account, Platt wants a suggestion to appear in the app to open a CD or a money market account.
One caveat: Platt resists the term “to drive,” as in, this effort driving customers to this or that channel.
“I don’t want to try to steer people into a store or to have to do something online if their preference is otherwise,” Platt says. She considers that the goal is to make all channels outstanding so each works for the customer and the bank.
Key insight: “Driving” may be futile anyway. “The reality of human behavior is that people are going to move across these channels, and that’s not going to change anytime soon,” says Platt. Meanwhile, TD stores are selectively being reconfigured to address the shift towards consultation and focuses on mass affluent and wealth management.
Read more: Storytelling Is Hot. But Is Your Bank Telling the Right Stories to the Right People?
Improved Cross-Selling With Better Data Analytics
Creating the opportunities to turn single-product relationships into broader relationships depends on making use of data that the bank already has. Platt says the challenge goes beyond the basics of piercing data silos within the institution — what do you do with the data after you’ve got it together?
“We’ve got to get to one collective view on what is most effective, at evaluating who to go after, what we think we can produce, and how we’re going to measure it,” Platt says.
Key insight: “There’s no secret sauce around this, no single technology-based answer, as much as it comes down to people, and to alignment and agreement on key objectives,” Platt explains.
Part of the alignment is deciding what the bank is trying to achieve in each project, pulling in analytics from multiple places, “and maybe asking one person to hold the pen on it and to consolidate all of the information,” according to Platt.
Constant repetition goes with the job. For Platt, this challenge isn’t one and done.
“We do this all the time, it feels like a meeting I have once a day. The point is how do we centralize the data to get to the right source of truth that we’re going to use to propel us forward?” says Platt.
The goal: “Ultimately,” says Platt, “there’s some equation that we need to get to that says, here’s the total population we could be going after on this campaign or effort, and we have to isolate where we think the greatest opportunity is, and move from there.”
Read next: How BMO is Leaning into Fundamentals to Drive More U.S. Deposits


